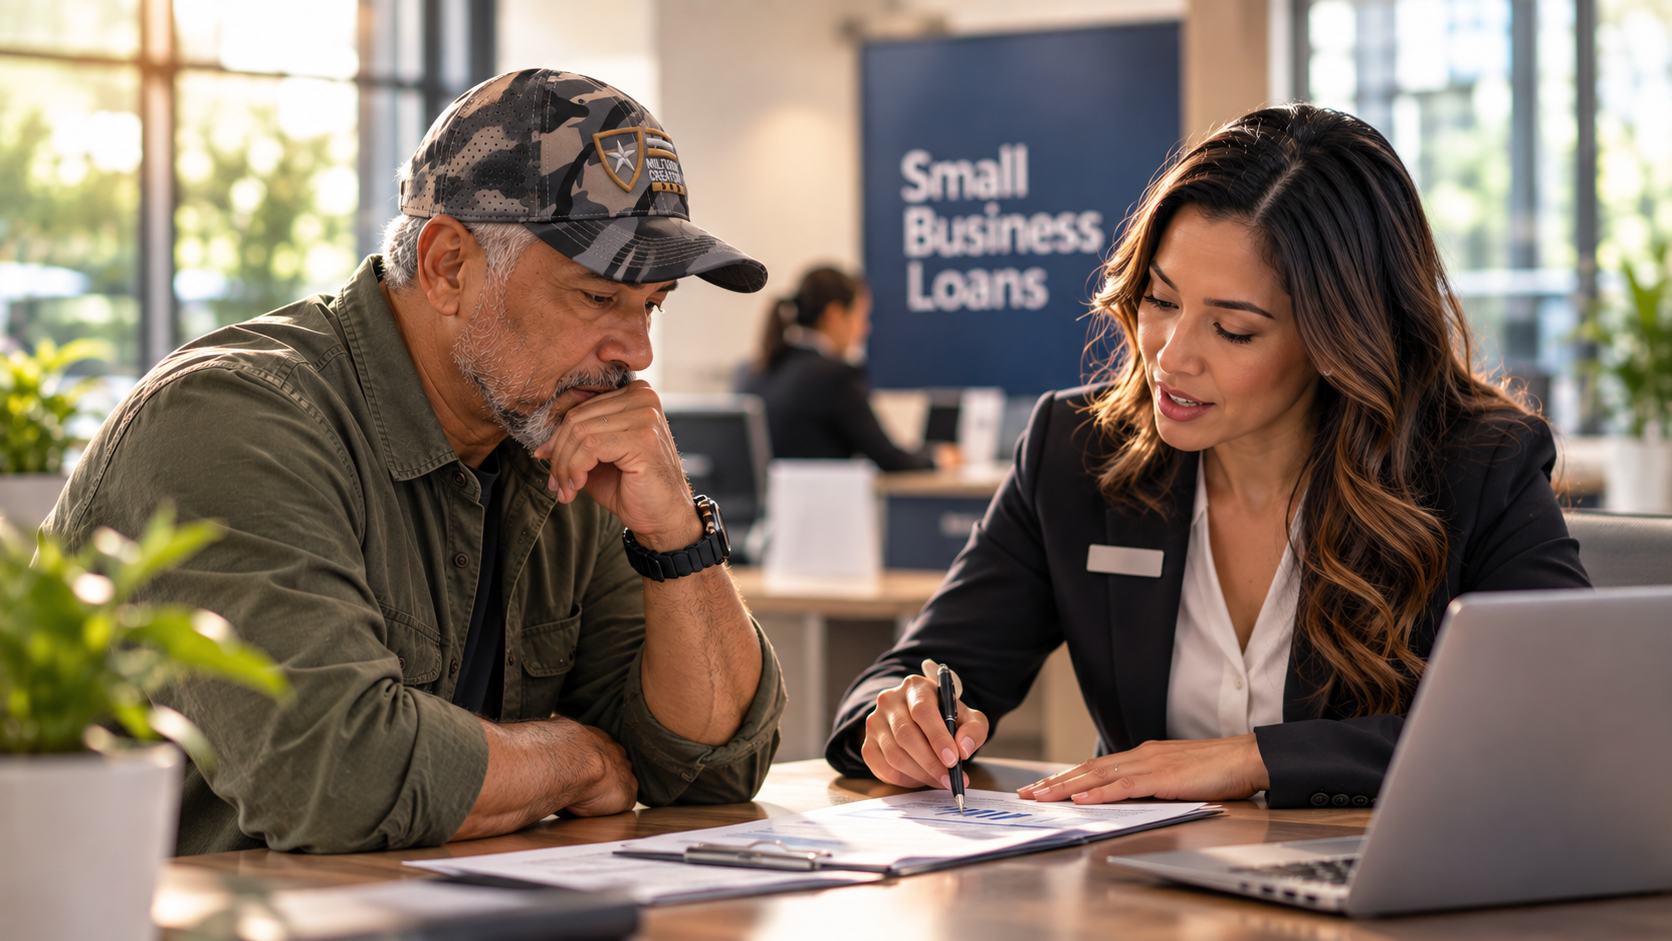
There are well over 1.5 million veteran-owned businesses in the United States, and by several measures they outperform the average small business on survival rate. That combination, real staying power paired with real financing friction, is exactly what makes the funding gap so frustrating. This isn't a story about veteran entrepreneurs being worse credit risks. It's a story about a lending system that hasn't fully caught up to that reality yet.
The gap, in real numbers
Veteran-owned small businesses have historically received a share of SBA loan volume that runs below their share of overall business ownership in the country, and government watchdog reviews have specifically flagged that the SBA hasn't always had strong procedures in place for tracking and reporting on veteran lending outcomes. Lenders have also been shown to classify veteran-owned businesses as medium or higher credit risk more often than non-veteran businesses, even though independent analysis has found the actual low-risk classification rate for veteran-owned businesses is close behind that of non-veteran businesses, not meaningfully worse.
Where the friction actually comes from
Part of it is genuinely structural rather than personal. Military service can create real gaps in a traditional civilian credit history, periods overseas, frequent moves, and a career path that doesn't always generate the same paper trail a conventional loan underwriter is trained to look for. Part of it is a documented pattern called the discouragement effect: veteran entrepreneurs, like several other underrepresented groups in small business lending, are more likely to expect a denial and simply not apply, even in cases where they would likely qualify. That means the real financing gap is probably larger than raw denial statistics alone suggest, since it doesn't capture the applications that never got submitted.
Limited access to the kind of informal financial mentorship and lending relationships that often come from years in a single civilian industry is another real factor. A first-time entrepreneur transitioning directly from service, however capable, frequently lacks the existing banking relationships and financial network a civilian entrepreneur might already have built over the same span of years.
What actually moves the needle on approval
Come to the table with two years of tax returns, clean financial statements, and a specific, well-documented business plan, since incomplete documentation is one of the most common and most fixable reasons any small business, veteran-owned or not, gets denied. Use the SBA's Veterans Advantage program specifically, which waives the upfront guarantee fee on loans under a certain threshold, meaningfully lowering the cost of capital at the exact moment you need it most.
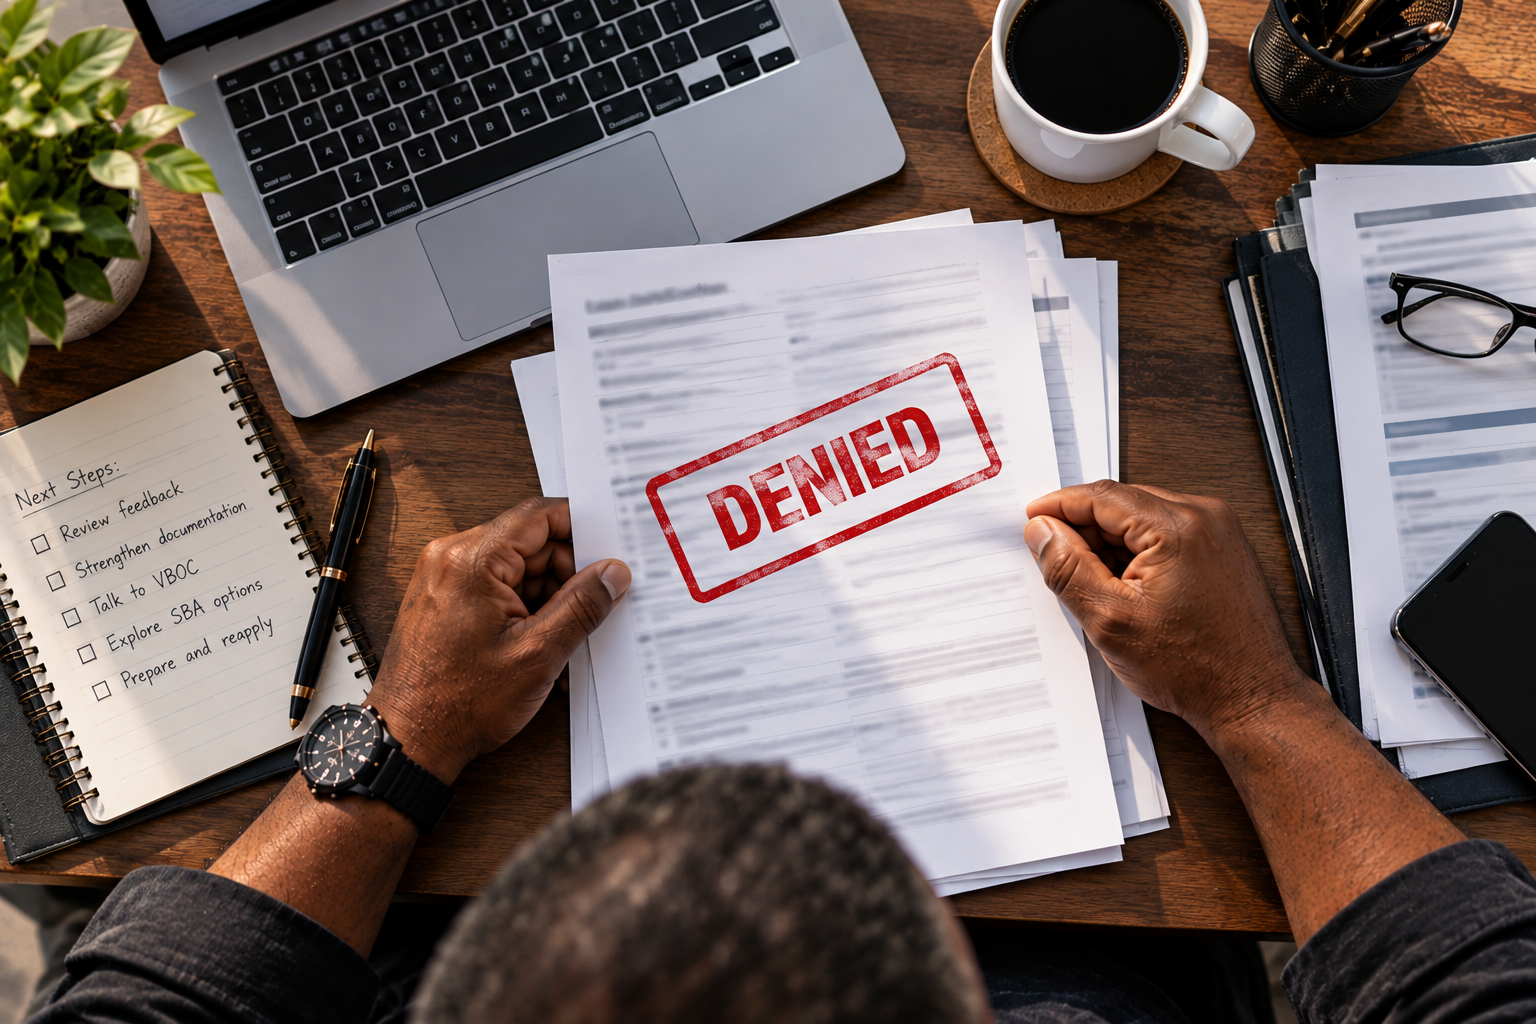
Don't stop at the first "no." A denial from one lender is a data point, not a verdict, and Community Development Financial Institutions in particular have expanded veteran-focused lending with more flexible underwriting than traditional banks typically apply. Veteran Business Outreach Centers, funded specifically to provide free counseling and financial education to veteran entrepreneurs, exist precisely to help you build the kind of application that gets approved, not just submitted.
The gap is closing, slowly, and you don't have to wait for it to close before you apply
Policy attention to this exact problem has increased in recent years, with SBA fee reductions and growing lender awareness of the veteran market segment cited as reasons for cautious optimism. That's real progress, but it's also not a reason to wait. The specific advantages available right now, waived fees, veteran-focused CDFIs, free VBOC counseling, exist because this gap is well documented and actively being worked on, and using them is how individual veteran entrepreneurs get funded while the broader system continues to catch up.